Do simple momentum signals survive transaction costs?
A pre-registered plan to test a classic momentum signal on public data, then charge it realistic trading costs.
Published
1 October 2026
Momentum, buying recent winners and selling recent losers, is one of the most studied patterns in finance. This study sets out, before looking at results, how I will test a simple version on freely available data and how much realistic trading costs reduce its returns. Results will be added here when the analysis is done.
Status: study design. There are no results yet. I am writing the method down before running the analysis, so that I cannot quietly change it after seeing the numbers.
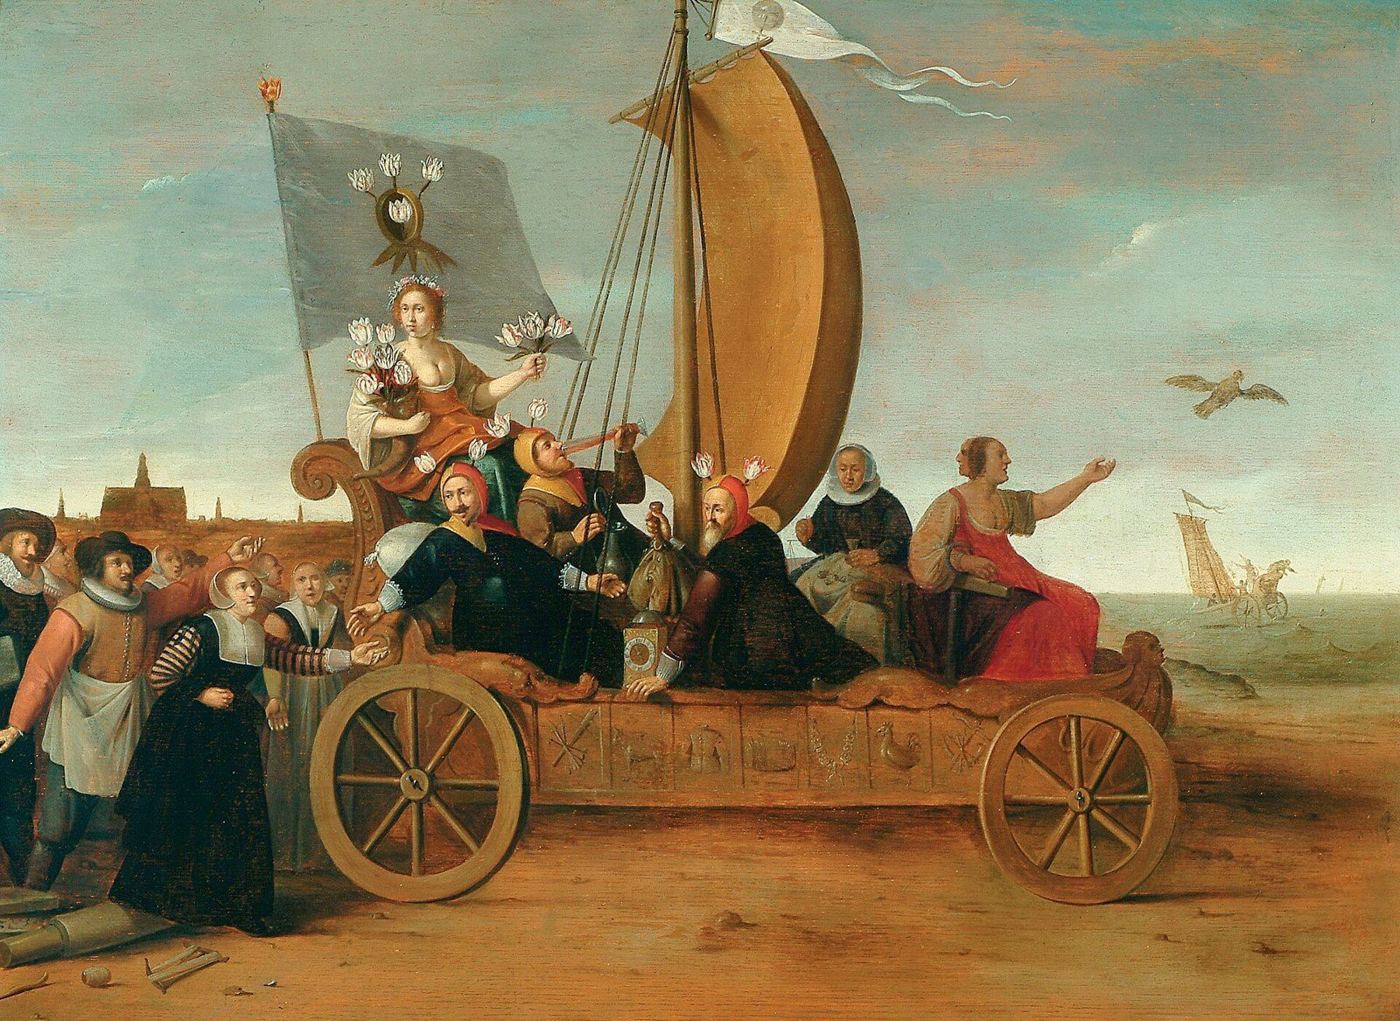
Markets have always had their fashions. In the Dutch Republic of the 1630s, the prices of rare tulip bulbs rose so fast that contracts for single bulbs changed hands for sums that later writers found almost unbelievable, before the market collapsed in February 1637. Historians now think the episode was smaller and less ruinous than its legend suggests, but it has become the standard example of prices that keep rising simply because they have been rising. Economists have spent a great deal of effort on a much more modest and more measurable version of that pattern, and it is the subject of this study.
The question
Stocks that have risen over the past year tend to keep rising for a while, and recent losers tend to keep falling. Narasimhan Jegadeesh and Sheridan Titman documented this in 1993, in a paper called Returns to Buying Winners and Selling Losers. They found that a portfolio that bought the best performers of the previous three to twelve months and sold the worst earned substantial returns over the following months, returns that standard models of risk could not explain. The effect has since been found across many countries and many kinds of asset, from shares to currencies and commodities. Tobias Moskowitz, Yao Hua Ooi and Lasse Pedersen later described a related pattern in 2012, time-series momentum, in which an asset’s own past return predicts its future return, across dozens of futures markets. Momentum is now one of the most studied patterns in finance, and one of the hardest to explain away.
The open question is how much of that return survives once you pay to trade. Momentum strategies trade often, because the list of winners and losers changes every month. And the losers they sell short are frequently small, illiquid stocks that are expensive to trade and sometimes hard to borrow. Several papers have argued that trading costs eat a large part of the profits that appear on paper. David Lesmond, Michael Schill and Chunsheng Zhou (2004) concluded that once realistic costs were included, much of the apparent profit disappeared. Robert Korajczyk and Ronnie Sadka (2004) looked at how large a momentum fund could grow before its own trading moved prices against it, and found that some versions of the strategy could remain profitable at a considerable size. The two papers reached different conclusions about how much is left, which is part of why the question is still interesting.
My question is deliberately narrow. Does a simple, long-only momentum rule, applied only to large and liquid stocks, still beat its benchmark after realistic costs? Restricting the test to large stocks and to buying, without short selling, removes the most expensive parts of the classic strategy. If momentum survives costs anywhere, it should be here.
Data and rule
I will use daily prices for the members of a broad large-cap index, adjusted for splits and dividends, from a free public source, over as long a period as that source allows. The first year will be used only to build the first signal. The benchmark will be the same index weighted equally, so that the comparison is fair: an equally weighted momentum portfolio should be compared with an equally weighted market, not with one dominated by the largest companies.
Free data has one known weakness that matters a great deal here. It usually lists only the companies that are in the index today, which introduces survivorship bias. Companies that failed, were taken over or were removed from the index are missing from the history, and since those are disproportionately the losers, any strategy tested on the survivors looks better than it would have been in reality. I will report this clearly alongside the results, and if possible I will repeat the test on a dataset that records the index’s historical membership.
The rule is the standard one from the academic literature. At the end of each month, rank every stock by its return over the past twelve months, skipping the most recent month, since very short-term returns tend to reverse rather than continue. Buy the top tenth of the ranking in equal weights. Hold them for one month, then repeat the ranking and rebalance.
Costs, and what counts as surviving
Every trade will be charged a cost, and I will test three levels: 5, 15 and 30 basis points for each side of a trade, covering the range from a cheap broker trading very liquid stocks to a deliberately pessimistic case. I will also report turnover, the share of the portfolio replaced each month, because turnover is what turns a small cost per trade into a large cost per year.
The strategy will count as surviving if, after costs, it beats the equally weighted benchmark by a margin that is unlikely to be due to chance. I will judge that with a simple t-test on the monthly excess returns, and also by running the test separately on the first and second halves of the period. A result that only appears in one half will be reported as fragile, since patterns in financial data have a habit of weakening once they are published and traded on.
When the analysis is done, I will publish the code, the exact data source, every result including the failures, and a short discussion of what the numbers can and cannot tell us.
Ayoub Khallok keeps this archive of essays, research, lessons and notes, written to understand things more clearly. More about Ayoub.